
FIRPTA Withholding for Foreign Sellers: A Practical Guide
Selling U.S. property as a foreign owner? The buyer usually withholds 15% of the gross price, not your profit. We explain who withholds, when rates drop, how Form 8288-B works and how to recover overpaid tax.

16.10.2026

21 minutes

November 12, 2026
Start With the Amount Withheld, Not the Final Tax
FIRPTA withholding is a federal tax-collection mechanism under Internal Revenue Code §§897 and 1445. When a foreign person sells a U.S. real property interest, the buyer generally must withhold 15% of the amount realized, not 15% of the seller's profit. This payment is credited against the seller's actual U.S. income-tax liability, which is determined on a tax return. A buyer who fails to collect and remit required withholding can face liability for the tax, penalties and interest.
For a Miami seller planning another purchase, the immediate concern is how much cash will remain available after closing. A mortgage payoff does not reduce the withholding base to net proceeds. Missing taxpayer identification numbers or late planning for reduced withholding can also delay access to funds.
FIRPTA applies nationwide, including in Florida despite its lack of individual income tax. Throughout this guide, "foreign" refers only to federal tax status, not a housing preference or a judgment about nationality or a neighborhood. The main workflow concerns a foreign individual selling directly owned residential property.
We explain the calculation, closing responsibilities and post-sale filing process, followed by a 15-step checklist. This guide is educational, not legal or tax advice. Transaction-specific decisions belong with a qualified U.S. international tax professional and, where appropriate, a real-estate attorney.
What Is FIRPTA, and Who Does It Cover?
The Foreign Investment in Real Property Tax Act makes a foreign person's gain or loss from a U.S. real property interest subject to U.S. federal taxation. Section 897 establishes the tax treatment, while §1445 provides the separate withholding mechanism. These federal rules apply whether the property is in Miami, Orlando or New York.
Under 26 U.S.C. §897, the gain or loss is generally treated as connected with a U.S. trade or business. The buyer's withholding helps collect the tax before the seller files the return.
- Transferor: the seller or other person disposing of the interest.
- Transferee: the buyer or other person receiving the interest.
- Withholding agent: the person responsible for collecting and remitting withholding, generally the buyer in a direct sale.
- USRPI: a U.S. real property interest.
Who Is a Foreign Person for FIRPTA?
A foreign person generally includes a nonresident alien individual or a foreign corporation, partnership, trust or estate. Entity classification can change who is treated as the seller and which withholding rules apply.
Citizenship alone does not determine FIRPTA status. An individual who meets the green-card test or substantial-presence test is generally a U.S. tax resident, subject to applicable exceptions. The IRS explains these residency tests in Publication 519.
Our recommendation is to confirm each owner's federal tax status before listing. A foreign passport or an overseas mailing address is not enough to decide the withholding treatment.
What Counts as a U.S. Real Property Interest?
A USRPI generally includes U.S. land and buildings, certain associated personal property, and certain interests in U.S. real property holding corporations. Ordinary ownership of South Florida condos falls within the direct real-property category.
If the transferred asset is not a USRPI, FIRPTA withholding does not apply to that asset. Whether a corporate interest or a mixed-asset transaction qualifies requires a technical review.
FIRPTA Withholding and the Seller's Actual U.S. Tax Use Different Calculations
FIRPTA withholding generally starts with gross consideration, while the seller's actual federal tax depends on taxable gain and the applicable tax rules. Withholding can exceed or fall short of that liability. The seller reconciles the difference through a U.S. income-tax return.
The IRS treats gains and losses from a foreign person's U.S. real property interests as effectively connected income. This means the sale falls within the federal income-tax framework for income connected with a U.S. trade or business, even when the owner lives abroad.
At a practical level, gain generally starts with the amount realized less allowable selling expenses and adjusted basis. Adjusted basis reflects acquisition costs and qualifying improvements, reduced by applicable depreciation and other adjustments. Depreciation recapture can change how some gain is taxed.
For example, an owner selling previously rented Downtown Miami condos needs the depreciation records as well as the original purchase price. Comparing purchase and sale prices alone can understate taxable gain.
There is no universal final capital-gains rate for every foreign seller. Holding period and seller classification affect the result. A low gain or loss also does not automatically stop gross-proceeds withholding at closing.
How the General 15% FIRPTA Withholding Is Calculated
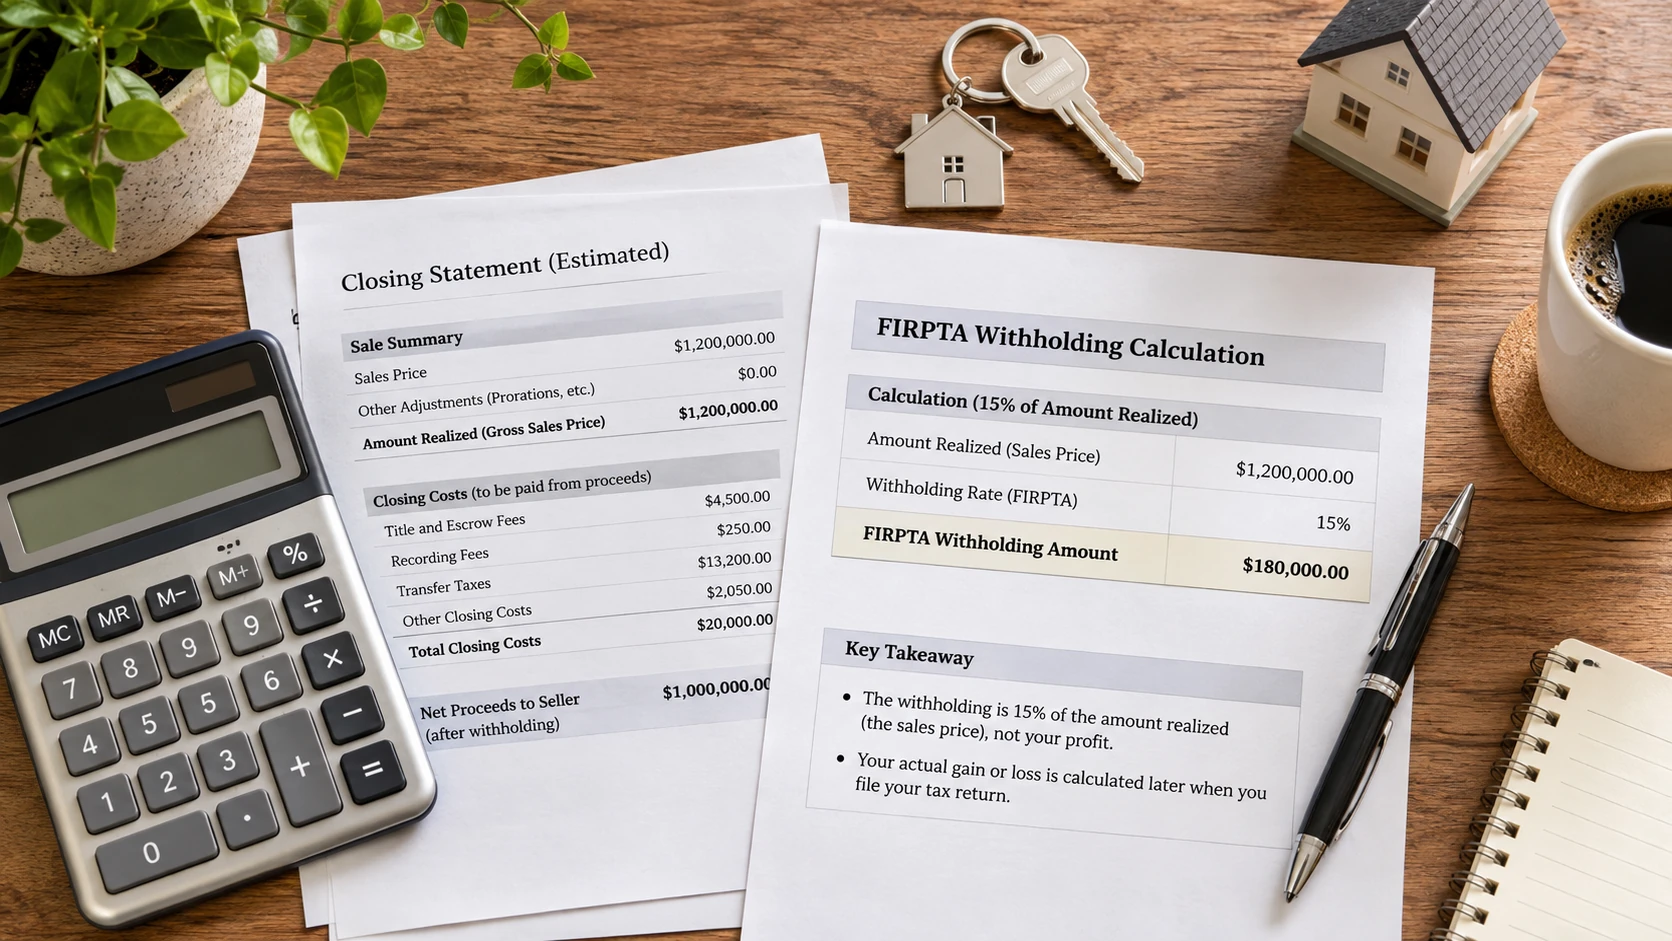
The general FIRPTA withholding rate is 15% of the amount realized by the foreign seller. The base is not profit or cash remaining after mortgage repayment and closing costs. A qualifying residence purchase, an IRS withholding certificate or another applicable exception can change the required withholding.
The general rule appears in 26 U.S.C. §1445. Applying 15% only to the seller's net proceeds can produce under-withholding and expose the buyer to liability.
What "Amount Realized" Means
According to the IRS FIRPTA overview, amount realized generally includes:
- Cash paid or to be paid.
- The fair market value of other property transferred.
- Liabilities assumed by the buyer or liabilities to which the property remains subject immediately before and after transfer.
In an illustrative $800,000 sale subject to the general rate, withholding is $120,000. That remains the calculation even if mortgage repayment and other costs leave only $200,000 before FIRPTA withholding.
When planning a sale of Miami Beach real estate, the seller's estimated closing statement should show mortgage repayment and FIRPTA withholding separately. That gives the owner a usable cash estimate before committing sale proceeds elsewhere.
Who Is Responsible for FIRPTA Withholding at Closing?
In most direct real-estate sales, the buyer is the FIRPTA withholding agent. The buyer must ensure that required withholding is collected, reported and paid. Having a title company prepare the paperwork does not remove the buyer's statutory responsibility.
The seller must provide accurate tax-status information and taxpayer identification details. The seller must also give the required notice if applying for a withholding certificate.
For a buyer purchasing Brickell Key real estate, seller-status documentation belongs in the contract-stage review. Waiting until the final settlement statement leaves less time to resolve a missing certification or a pending certificate application.
- Buyer: confirms the withholding treatment and remains responsible for compliance.
- Seller: supplies identification, status information and application notices.
- Closing team: handles agreed fund-holding, document preparation and remittance tasks.
- Tax professional: determines transaction-specific tax treatment and prepares the relevant tax calculations and filings within the agreed engagement.
When the FIRPTA Residence Exception Changes the Rate
A qualifying individual-buyer residence purchase generally requires no withholding at $300,000 or less and 10% withholding above $300,000 through $1,000,000. Above $1,000,000, the general 15% rate applies. Eligibility depends on the buyer's planned use, not the seller's previous occupancy.
The actual transferee must qualify as an individual. An entity purchase should not be assumed eligible for a residence exception. Any disregarded-entity ownership arrangement needs tax review before applying a reduced rate.
Under the IRS residence-use test, the buyer or a family member must have definite plans to occupy the property for at least 50% of the days anyone uses it. This test applies separately during each of the first two 12-month periods after transfer. Vacant days do not count.
A buyer's residence-use statement helps document the intended use. Calling the property a vacation home or saying that the seller previously lived there does not establish eligibility.
The $300,000 Residence Exception
When the individual-buyer and residence-use requirements are met, an amount realized of $300,000 or less generally requires no FIRPTA withholding. This exception removes withholding, not the seller's underlying tax or applicable return-filing obligations.
The 10% Rate Through $1 Million
The Form 8288 instructions provide the reduced 10% rate for qualifying residence purchases above $300,000 and not exceeding $1,000,000. Once the amount realized exceeds $1,000,000, the general 15% rate applies to the entire amount. It is not a blended rate applied only to the excess.
When a Nonforeign Certification Removes the Withholding Requirement
FIRPTA withholding generally does not apply when the seller provides a valid certification of nonforeign status. Often called a FIRPTA affidavit, it must include the seller's name, U.S. taxpayer identification number and address. The seller must sign it under penalties of perjury.
A valid Form W-9 can serve as certification in appropriate circumstances. A qualified substitute, such as an eligible closing attorney or title company, can hold the certification under the applicable procedures. Neither the buyer nor the substitute can rely on a certification they know is false.
Other possible grounds for a FIRPTA exemption or withholding relief include:
- The transferred asset is not a U.S. real property interest.
- The amount realized is zero.
- The buyer is a specified governmental body.
- An IRS withholding certificate excuses withholding.
- A qualifying nonrecognition provision or treaty applies and the required notice procedures are satisfied.
Each ground has its own requirements. A transaction with no cash payment, for example, does not necessarily have zero amount realized if liabilities are involved.
How Form 8288-B Can Reduce FIRPTA Withholding
A FIRPTA withholding certificate authorizes reduced or eliminated withholding when the applicable requirements are met. A common reason to apply is that statutory withholding materially exceeds the seller's maximum U.S. tax liability. Filing an application alone does not authorize the closing team to release the money.
The IRS uses Form 8288-B for common application categories, including maximum-tax-liability claims. Other grounds for certificate relief can involve exempt gain, nonrecognition or qualifying payment arrangements. The appropriate application procedure depends on the category.
Under its withholding certificate guidance, the IRS generally aims to act within 90 days after receiving all required information and taxpayer identification numbers. That is not an approval guarantee or a promised release date.
For sellers with a high adjusted basis or a loss, we recommend evaluating this option as soon as a binding contract exists. The seller applying for a certificate must notify the buyer in writing on the day of transfer or the day before. Earlier coordination gives the closing team time to prepare the fund-holding instructions.
What Happens if the Certificate Is Pending at Closing?
If a qualifying application was submitted on or before the transfer date and remains pending, the statutory amount must still be withheld at closing. The filing rules can allow the buyer to defer reporting and remitting that amount while the IRS considers the application.
The required amount must generally be reported and paid within 20 days after the IRS mails the certificate or denial notice. An approved certificate may reduce the payment. Funds may be released to the seller only as permitted by the applicable outcome.
Written closing instructions should identify who holds the funds and who monitors IRS correspondence. They should also specify who makes the payment and how any authorized excess is released.
Examples Show Why Price and Buyer Use Matter
These illustrative calculations show withholding, not final income tax. They assume the stated amount realized and no additional certificate or exception. Actual treatment depends on the transaction facts and applicable IRS rules.
Example 1: An $800,000 Sale at the General Rate
A foreign individual sells directly owned U.S. property for $800,000 to an individual buyer who will not satisfy the residence-use test. Withholding is $800,000 × 15% = $120,000.
The $120,000 is withheld even if taxable gain is only $150,000. That comparison does not establish the final tax rate or liability. If the estimated maximum U.S. tax is materially lower than $120,000, a withholding-certificate application may be useful.
Example 2: Residence Purchases at Three Price Points
The examples below all assume an individual buyer who satisfies the residence-use test. Withholding is zero on a $250,000 purchase and $75,000 on a $750,000 purchase. At $1,200,000, the general rate produces $180,000 of withholding.
Illustrative calculations using IRS residence thresholds. These amounts are withholding, not final tax.
If the buyer does not satisfy the residence requirements, the general 15% rule applies unless another exception or certificate provides relief.
Forms 8288 and 8288-A Are Generally Due Within 20 Days
The buyer generally files Form 8288 and pays the withholding by the 20th day after transfer. A separate Form 8288-A accompanies the filing for each foreign seller from whom tax was withheld. A timely pending withholding-certificate application can change this reporting and payment deadline.
The IRS explains these requirements in its reporting and payment guidance. Missing the applicable deadline can expose the buyer to penalties and interest.
Once identification requirements are satisfied, the IRS stamps Copy B of Form 8288-A and sends it to the seller. This statement supports the seller's withholding credit.
| Form | Purpose | Practical distinction |
|---|---|---|
| Form 8288 | Reports and transmits withholding | Generally the buyer's withholding return |
| Form 8288-A | Records withholding for each foreign seller | Supports the seller's credit |
| Form 8288-B | Requests a withholding certificate | An application is not approval |
| Form 1099-S | Reports real-estate proceeds | Does not replace FIRPTA forms |
The person responsible for closing may have a separate Form 1099-S reporting obligation. Before funds are disbursed, the parties should confirm who will submit each required filing and retain proof of payment.
ITIN and TIN Requirements Can Affect the Seller's Credit
Buyers and foreign sellers generally need U.S. taxpayer identification numbers for FIRPTA filings. A nonresident alien individual who is ineligible for a Social Security number may need an Individual Taxpayer Identification Number, or ITIN. Entities generally use an Employer Identification Number, or EIN.
The IRS ITIN guidance allows an eligible seller to submit Form W-7 with Form 8288-B under FIRPTA Exception 4 after a legally binding contract creates the tax need. Planning can begin before listing, but an application without a valid tax reason can be denied.
The Form W-7 instructions specify identity documentation and supporting evidence for the exception. The tax preparer should check the current requirements before submission.
What if the Seller Has No TIN at Closing?
A missing seller TIN does not suspend the buyer's withholding, filing or payment obligations. The IRS may process Forms 8288 and 8288-A without issuing the normal stamped Copy B until the missing identification information is supplied.
The seller may need to obtain an ITIN and provide substantial evidence of withholding to claim the credit. This can delay a refund, so identification problems should be addressed before the closing date.
How a Foreign Seller Claims FIRPTA Credit or a Refund
The seller reports the actual gain or loss on the required U.S. income-tax return and claims FIRPTA withholding as a credit. A nonresident alien individual generally uses Form 1040-NR. Withholding above the final liability may produce a refund, while insufficient withholding can leave a balance due.
The IRS provides the return and related instructions on its Form 1040-NR page. The seller generally attaches stamped Copy B of Form 8288-A or uses other permitted evidence when the stamped copy is unavailable.
A refund requires IRS processing, and its timing should not be assumed when planning another purchase. The tax professional can also evaluate whether an available early-refund procedure applies. For cash needed immediately after closing, pre-closing certificate planning is especially important.
Joint U.S. and Foreign Owners Need Separate Allocations
When U.S. and foreign persons sell jointly owned property, IRS guidance allocates the amount realized according to capital contributions. Only the foreign owners' allocated shares are subject to foreign-seller withholding. For this allocation, spouses are treated as having contributed 50% each.
The parties cannot assign the entire sale to a U.S. spouse merely to avoid FIRPTA. Ownership and contribution records should support the allocation used at closing.
Each foreign seller from whom tax is withheld needs a separate Form 8288-A. Matching each seller's name and TIN to the correct withholding amount helps prevent later credit discrepancies.
Entities, Exchanges and Exclusions Require a Different Review
The direct-sale workflow changes when ownership or tax treatment is more complex. Entity sales, treaty claims and nonrecognition transactions can involve different withholding bases or procedures. These cases require a qualified U.S. international tax professional before closing instructions are finalized.
LLCs, Corporations, Partnerships, Trusts and Estates
An LLC does not automatically avoid FIRPTA. Its federal tax classification and ownership determine which person is treated as the seller and which rules apply. A disregarded entity cannot simply certify nonforeign status in place of a foreign owner.
The IRS entity procedures explain special rules for corporations, partnerships, trusts, estates and certain real-estate investment entities. Section 1445(e) covers specified entity transactions. Section 1446(f) separately addresses certain transfers of partnership interests.
For example, a foreign corporation distributing a USRPI can face withholding of 21% of recognized gain rather than 15% of the amount realized. The relevant corporate and other withholding rules are addressed in IRS Publication 515.
For entity-owned South Florida commercial real estate, the review should distinguish a property sale from a transfer of ownership interests. Similar economic outcomes can create different reporting obligations.
A transaction involving businesses for sale in South Florida may include real estate alongside operating assets. FIRPTA analysis depends on the assets or interests transferred, not simply the description "business sale."
Nonrecognition Transactions and Treaty Claims
Nonrecognition means that a qualifying tax rule postpones or prevents recognition of gain or loss. Certain Code provisions or treaties can support withholding relief when the required notices and conditions are satisfied. For notice-based relief, the buyer generally must send the required notice to the IRS by the 20th day after transfer.
A treaty claim does not automatically eliminate FIRPTA. The adviser must establish both the substantive tax treatment and the correct withholding procedure.
Section 1031 Exchanges
A foreign seller cannot assume that arranging a like-kind exchange eliminates withholding. The ordinary nonrecognition-notice procedure is unavailable for exchanges that do not qualify for full nonrecognition. It is also unavailable for deferred exchanges that remain incomplete when the FIRPTA filing is due.
These transactions may require a withholding certificate. We recommend resolving the withholding plan alongside the exchange structure, rather than treating FIRPTA as paperwork to address afterward.
The Section 121 Home-Sale Exclusion
The ordinary notice-of-nonrecognition procedure cannot be used for the §121 principal-residence exclusion. Even if the seller qualifies to exclude gain, withholding relief generally requires a certificate application. Eligibility for the exclusion and permission to reduce withholding are separate questions.
Florida's Individual Tax Rules Do Not Remove FIRPTA
Florida has no individual income tax and therefore no separate Florida individual capital-gains tax. Federal FIRPTA withholding and federal return obligations still apply. Corporate sellers can also face Florida tax and filing requirements.
The Florida Department of Revenue confirms the individual treatment in its capital-gains tax guidance. This state rule does not determine the seller's federal liability.
Florida's corporate income tax can apply to corporations and entities taxed federally as corporations that do business or earn income in Florida. Foreign corporations earning Florida income can have filing obligations.
Property in another state may also trigger that state's income, withholding or transfer taxes. FIRPTA should never be treated as a complete list of taxes and transaction charges associated with a sale.
Documents a Foreign Seller Should Gather Before Closing
Identity and basis records allow the tax professional to estimate gain, evaluate reduced withholding and prepare the return. Collect them early, especially when records are held abroad or by a former property manager. Missing documentation can make otherwise valid basis adjustments harder to substantiate.
- Original purchase closing statement and acquisition records.
- Deed and documents establishing ownership.
- Capital-improvement invoices and supporting payment records.
- Depreciation schedules and rental tax returns.
- Prior U.S. returns, including applicable Forms 1040-NR.
- Passport and other required identity documents.
- SSN, ITIN or EIN documentation for each seller.
- Signed sale contract and estimated closing statement, once available.
- Entity formation, tax-classification and ownership records.
- Relevant treaty, residency and tax-status documentation.
For an owner who has renovated Allapattah real estate, improvement records should distinguish capital work from routine repairs. The tax professional decides which costs affect basis and how prior deductions change the calculation.
A 15-Step FIRPTA Checklist From Listing to Tax Filing
Start with seller status and ownership, then resolve withholding and identification requirements before closing. After the sale, preserve evidence and complete the tax-return process. This sequence helps keep the real-estate transaction aligned with the tax professional's work.
Before the Contract: Steps 1-5
- Confirm whether each owner is a foreign person for FIRPTA purposes.
- Identify direct ownership or the entity structure and federal tax classification.
- Check each seller's SSN, ITIN or EIN status.
- Gather basis, improvement, depreciation and prior closing records.
- Have a U.S. international tax professional estimate actual federal gain and tax.
From Contract to Closing: Steps 6-11
- Determine whether the buyer-residence exception applies and document the intended use.
- Decide whether to apply for reduced withholding using Form 8288-B.
- If an ITIN is needed, prepare Form W-7 under the appropriate FIRPTA exception after a binding contract creates the tax need.
- Give the buyer written notice of a withholding-certificate application within the required timing.
- Confirm written instructions for holding funds, monitoring an IRS decision and remitting payment.
- Check Forms 8288 and 8288-A information, each seller's TIN and the allocation of withholding at closing.
After Closing: Steps 12-15
- Keep the Closing Disclosure or settlement statement and evidence of withholding and remittance.
- Obtain the IRS-stamped Form 8288-A when issued and resolve identification discrepancies.
- File the required U.S. income-tax return and claim the withholding credit or refund.
- Review state, local and entity filing requirements for the property and seller.
How BonaDomus Supports FIRPTA Closing Coordination
BonaDomus supports the real-estate transaction and coordination with the professionals involved in closing. The qualified tax professional handles transaction-specific FIRPTA analysis and tax filings within the agreed engagement. The title or closing team handles its assigned settlement and withholding tasks.
Our practical recommendation is to bring the tax professional into the process before the contract whenever possible. That allows the parties to assess identification needs and possible certificate relief before setting expectations for the seller's available proceeds.
Whether a client is selling Little Havana real estate or another South Florida property, the contract timeline should reflect the actual tax-document requirements. A closing date should not depend on an assumed IRS approval or refund date.
Confirm FIRPTA status early and coordinate your sale with BonaDomus, a qualified U.S. international tax professional and an experienced title team. Agree in writing who calculates withholding, submits each filing and monitors every deadline.
Plan the Withholding and the Final Return Separately
The general FIRPTA rule collects 15% of the amount realized through the buyer, while the seller's final tax is settled through the U.S. income-tax return. Buyer-residence rules or an IRS certificate may reduce withholding. A pending certificate application still requires funds to be withheld at closing.
Before acting, have the responsible professionals check current IRS forms, instructions and mailing addresses. Entity ownership and special tax claims require their own review. A clear assignment of responsibilities protects the buyer's compliance and gives the seller a more reliable estimate of available closing proceeds.
Is FIRPTA withholding the foreign seller's final tax on a U.S. property sale?
No. FIRPTA withholding is a collection mechanism under IRC §1445, generally 15% of the amount realized. The seller's actual federal tax is calculated on a U.S. income-tax return, usually Form 1040-NR for a nonresident alien individual, based on gain, adjusted basis, depreciation and tax status. Withholding above the final liability can be refunded, and any shortfall is a balance due.
Does paying off the mortgage at closing reduce the FIRPTA withholding amount?
No. The withholding base is the amount realized, which includes cash paid, the fair market value of other property transferred and liabilities assumed or to which the property remains subject. In an illustrative $800,000 sale at the general rate, withholding is $120,000 even if mortgage repayment and costs leave the seller only $200,000. Applying 15% to net proceeds can cause under-withholding and expose the buyer to liability.
If Form 8288-B is pending at closing, is any money withheld?
Yes. If a qualifying application was submitted on or before the transfer date, the full statutory amount is still withheld at closing, but remittance to the IRS can generally be deferred. The withheld amount, or a lower amount set by the certificate, is generally reported and paid within 20 days after the IRS mails the certificate or denial notice. Funds are released to the seller only as the outcome permits, so written closing instructions should name who holds the funds and monitors IRS correspondence.
Can the seller's past use of the home qualify the sale for the FIRPTA residence exception?
No. The residence exception depends on the buyer: an individual transferee, or a family member, must have definite plans to live in the property at least 50% of the days it is used during each of the first two 12-month periods after transfer, excluding vacant days. If met, withholding is generally zero at $300,000 or less and 10% above $300,000 through $1,000,000. Above $1,000,000, the 15% rate applies to the entire amount realized, not just the excess.
When should a foreign seller apply for an ITIN for FIRPTA purposes?
An eligible seller can submit Form W-7 together with Form 8288-B under FIRPTA Exception 4 once a legally binding contract creates the tax need. Applying earlier without a valid tax reason can lead to denial, although document preparation can start before listing. Without a TIN, the IRS may process the buyer's Forms 8288 and 8288-A but withhold the stamped Copy B, which can delay the seller's credit or refund.
Does holding Florida property in an LLC or using a 1031 exchange avoid FIRPTA withholding?
Not automatically. An LLC's federal tax classification and ownership determine who is the seller and which rules apply, and a disregarded entity cannot certify nonforeign status in place of a foreign owner. The ordinary nonrecognition notice cannot be used for like-kind exchanges without full nonrecognition, deferred §1031 exchanges incomplete when the filing is due, or the §121 exclusion, so these cases often need a withholding certificate. A U.S. international tax professional should review them before closing instructions are final.
Does Florida's lack of personal income tax change FIRPTA obligations for foreign sellers?
No. FIRPTA is federal law that applies nationwide, so withholding and the federal return still apply to Miami and other Florida sales. Florida imposes no individual capital-gains tax, but corporations and entities taxed federally as corporations that earn Florida income may have Florida corporate income tax filings. Property in other states can also trigger that state's income, withholding or transfer taxes.
- — Withholding Is Not Final Tax
- — Federal Rules and Seller Status
- — Withholding Versus Actual Tax
- — Calculating the Withholding Base
- — Buyer and Seller Responsibilities
- — Buyer Residence Rate Exceptions
- — Documenting Nonforeign Seller Status
- — Applying for Reduced Withholding
- — Illustrative Withholding Calculations
- — Forms and Payment Deadlines
- — Taxpayer Identification Before Closing
- — Claiming the Withholding Credit
- — Allocating Joint Owner Withholding
- — Transactions Needing Specialist Review
- — Florida and Federal Tax Layers
- — Records to Gather Early
- — Fifteen Steps Through Closing
- — Coordinating the Transaction Team
- — Protecting Cash and Compliance

