HOA Fees in Florida: What Condo and Home Owners Pay For
Understand Florida association fees, extra assessments and separate ownership costs, with a checklist and 16 answers to common buyer questions.

7.10.2026

9 minutes

October 9, 2026
Shared grounds and amenities require ongoing maintenance funded through the association’s budget.
When choosing a home in Florida, buyers usually compare price, location and layout. Before deciding what fits your budget, it also helps to understand the costs after closing. Condo listings and homes in association communities often have a separate line for HOA or maintenance fees. Here is what those payments cover, what you may owe on top of them and what to check before buying.
What is an HOA?
HOA stands for Homeowners’ Association. It is an owners’ association that manages shared community property and collects money to maintain it.
Condos are managed by a condominium association. Listings often call its assessments HOA or maintenance fees too. As a buyer, you need to know whom you will pay, how much and what the payment covers.
A single-family home may have no mandatory association. Townhouses can have different ownership structures, so check the documents to understand the owner’s responsibilities. A home’s appearance does not tell you who maintains its roof, exterior or lot.
What do association fees cover?
The expenses covered depend on the community. Payments commonly fund several things:
- Maintenance of common areas and grounds: cleaning, elevators, lighting and landscaping.
- Shared amenities and services: a pool, gym, clubhouse, security and staff, where provided.
- Insurance for association property.
- Savings for future repairs, known as reserves.
Association fees may cover pool maintenance and other shared services. Check the budget to confirm what is included.
Water, internet, trash collection, parking or lawn care may be included or billed separately. Check the budget and association documents for the exact breakdown.
Property taxes on your condo or home, your mortgage and your own insurance are usually separate expenses. The building’s policy does not replace coverage for your belongings and interior finishes. Homeowners also pay to maintain their own lot, pool and roof unless the community documents provide otherwise.
Why do fees differ?
Services, staffing, insurance, building condition and repair plans all affect the payment. Higher fees may reflect more services, but also costly maintenance or contributions to reserves. A low fee alone does not mean the property will cost less to own.
A community may charge separately for the tower and the shared grounds or facilities. The latter is often called a master fee. Ask whether it is included in the amount shown in the listing.
Fees can differ even between units in the same building: the condominium documents set each unit’s share of common expenses. Compare payments over the same period. Divide a quarterly payment by three to compare it with a monthly fee.
What additional assessments can you expect?
A special assessment is an extra charge, for example to replace a roof or repair the exterior. It may be due all at once or in installments. It is added to the regular assessment.
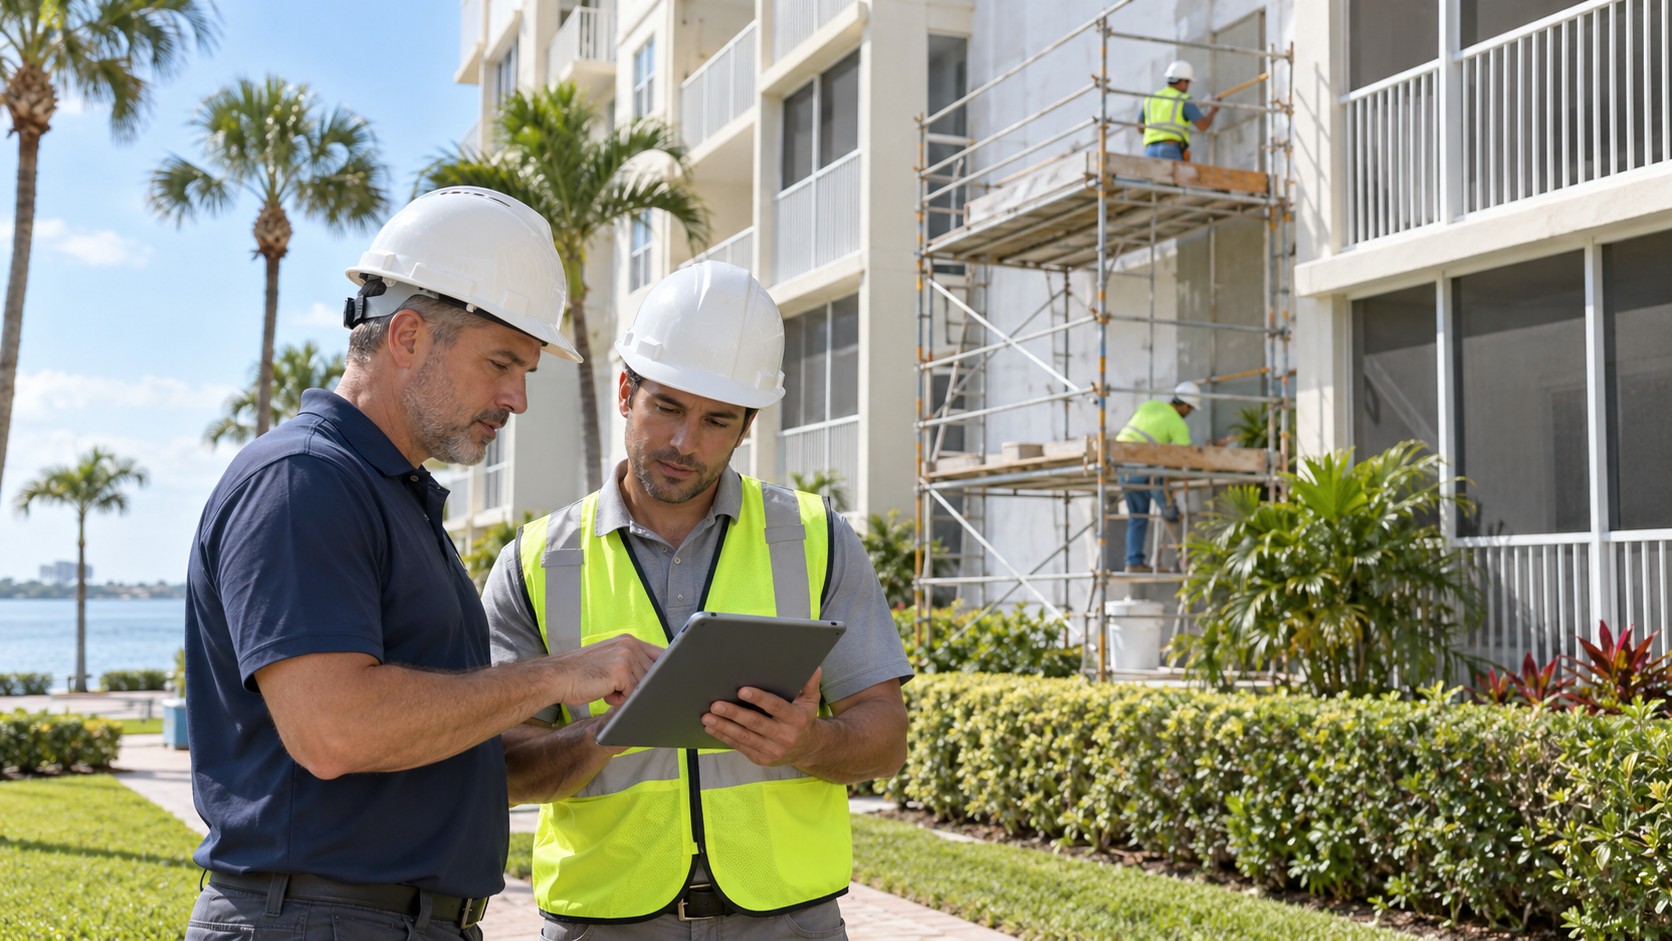
A special assessment may help fund exterior repairs. Check the amount assigned to the property and when payments are due.
Before buying, find out the total assigned to the property, how much has been paid, what remains and when it is due. If the association borrowed money for the work, ask how loan repayments affect your fees.
If a property is sold with an ongoing assessment, the contract should specify which portion the seller pays and which portion the buyer pays.
How to calculate monthly ownership costs
Add regular assessments from every association, special assessment installments, property taxes as a monthly amount, your own insurance and services not included in the association fee. Then add the mortgage payment if you are financing the purchase.
Illustrative example: $900 in regular assessments + $150 master fee + $300 special assessment installment = $1,350 per month payable to associations alone. This is a calculation example, not a rate for a particular community. Taxes, your own insurance and mortgage payments are additional.
A home without an HOA has no association fee, but grounds, equipment and repairs still cost money. Include those expenses when comparing it with a condo.
To estimate the full household budget, add food, transportation and healthcare. Our guide to the cost of living in Miami includes a sample calculation.
What to check before buying
Review the association’s budget, reserve balances and assessment decisions before buying.
Ask the seller and association for:
- The current budget, financial report and reserve balances.
- All regular assessments, payment frequency and included services.
- Special assessment decisions, outstanding loans and repair plans.
- Rules for rentals, parking, pets and renovations.
- For a condo: applicable building inspection and reserve study reports.
Condo documents may mention milestone inspections and SIRS. A milestone inspection evaluates the building’s structural condition. SIRS helps estimate the money needed for future repairs to key components. Check whether these requirements apply to the building, whether recommended work has been completed and how it is funded.
Building documents do not replace a condo inspection before buying. Arrange it separately to check the condition of the unit itself.
Before closing, an estoppel certificate is requested. It states association charges and outstanding balances for the property. Compare it with the contract and special assessment decisions.
Frequently asked questions
Do HOA and condominium fees mean the same thing?
Listings often use these terms for association payments. However, condo associations and homeowners’ associations have different structures and rules. Check the property’s documents to see exactly what the fee covers.
Does every single-family home in Florida have an HOA?
No. Mandatory fees apply to homes in communities with required association membership. A lack of gates or shared security does not mean there is no HOA.
Are HOA fees paid monthly?
Payments may be monthly, quarterly or annual. Convert all assessments to a monthly amount when comparing properties, but pay them according to the association’s schedule.
Why does one property have two association fees?
One payment may go to the building association, while a second master fee funds shared community grounds or facilities. Ask whether the listing adds them together or whether you need to add the second fee yourself.
Can I stop paying if I do not use the pool?
For a condo owner, choosing not to use shared amenities does not remove the obligation to pay a share of common expenses. Assessments also remain due when the unit is vacant or used only part of the year.
Can fees increase after I buy?
Yes. Insurance, maintenance, repairs and other association expenses change. Compare the current and previous budgets before buying and ask whether an increase is being discussed.
Does a low HOA fee mean lower ownership costs?
Not necessarily. It may cover fewer services, and major repairs may not yet be funded. Compare total ownership costs, building condition and planned work.
Can I negotiate an individual discount on HOA fees?
Mandatory assessments are calculated under the association’s rules. They are not a service price you can negotiate down with the seller. You can negotiate the purchase price and how certain closing costs are shared.
How is a special assessment different from a regular fee?
It is an extra charge for a specific expense, such as exterior repairs or roof replacement. It is billed separately from regular assessments. The association’s decision should state the amount, purpose and payment schedule.
Who pays a special assessment when a condo is sold?
The contract should specify how payments are split between seller and buyer. Check the full amount, outstanding balance and due dates. A verbal promise from the seller is not enough.
Can I pay a special assessment in installments?
Only if an installment schedule is provided or agreed with the association. Do not assume one is available without confirmation. For budgeting, spread the cost over months, but account for the actual due dates.
What are association reserves?
They are funds set aside for future repairs and replacement of shared property. They help spread costs in advance. Having reserves does not, by itself, rule out additional assessments.
What does an estoppel certificate show?
It states association charges and outstanding balances for the specific property. Review it before closing alongside the special assessment schedule. It does not replace reviewing the budget and building condition.
Can the seller’s unpaid assessments become the buyer’s problem?
Yes, unpaid assessments can also create obligations for a new owner. Check for outstanding balances and arrange for them to be settled before closing. Do not rely solely on the seller’s statements.
What happens if I stop paying HOA fees?
Interest and collection costs may accrue. Subject to the required legal process, an association may seek recovery through a lien and foreclosure. If you dispute a charge, request an itemized calculation and the dispute procedure.
Can an owner review the association’s financial records?
The law gives owners access to certain official records, with exceptions for protected information. Ask how to submit a request. Before buying, obtain the necessary documents through the seller and association.